


ECB Freezes Rates as Iran War Energy Shock Squeezes Europe

Europe’s central bank refused to choose between inflation and recession on Thursday, holding interest rates at 2.5 percent while warning that the Iran-war energy shock now threatens higher prices and weaker growth at the same time.
The European Central Bank left all three key rates unchanged on October 29: 2.5 percent on deposits, 2.65 percent on its main refinancing operations and 2.9 percent on marginal lending. The pause followed two increases this year as policymakers tried to stop higher oil and gas costs from spreading through wages and the wider economy.
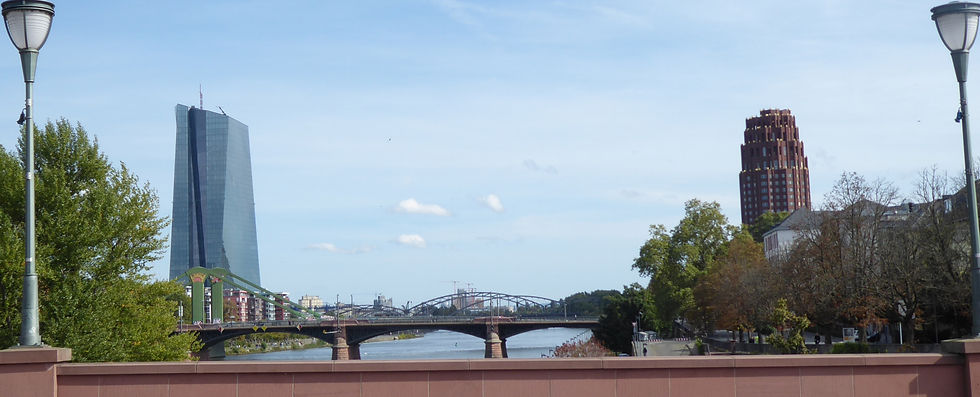
The decision did not declare victory. It exposed a bank trapped between incompatible demands.
“Energy prices have continued to rise, posing upside risks to the inflation outlook and downside risks to the growth outlook,” the ECB said. The bank added that underlying inflation remained broadly stable and that wages had not yet shown a material response. But it warned that the energy shock’s greater scale and duration could push inflation higher while cutting growth.
Euro-area inflation reached 3.8 percent in September, nearly twice the ECB’s 2 percent target. That headline number gives hawks an argument for another increase in December. Yet interest rates do not produce oil, reopen shipping lanes or end a regional war. They suppress demand by making mortgages, business loans and public borrowing more expensive.
That distinction matters for workers. Families cannot escape an energy shock by postponing heat, transport or food. Higher rates add another bill on top of the first one. The central bank’s preferred cure can slow wage growth and investment without reducing the geopolitical price embedded in fuel.
France has made the contradiction impossible to ignore. Investors now demand roughly 155 basis points more to hold ten-year French debt than German bonds, a decades-high premium. That spread means tighter credit is already doing part of the ECB’s work, but through a disorderly market punishment concentrated on one of the euro area’s largest economies.

The ECB acknowledged that financing conditions have tightened since its September meeting and said this would weigh on both inflation and growth. The euro fell about 0.3 percent after the decision, reaching its lowest level since May, while rate-sensitive government bond yields also declined. Markets read the pause as caution, even as economists continued to price another move before the end of the year.
Europe’s monetary union was built around one interest rate for economies with radically different debt burdens, industrial structures and energy exposure. That design looks most fragile when crisis hits unevenly. A rate high enough to discipline prices in one country can break investment or public finances in another.
The bank has tools to resist a bond panic. It can reinvest proceeds from earlier asset-purchase programs more flexibly, directing support toward pressured markets. It also holds the never-used Transmission Protection Instrument, designed to counter market moves that obstruct monetary policy across the bloc. Activating it, however, would force unelected officials to decide when France’s borrowing costs reflect legitimate risk and when they become an attack on the euro itself.
The policy dilemma now overlaps with a leadership crisis. Hours before the rate announcement, ECB President Christine Lagarde said she would leave on February 7, nine months early. Her successor will inherit a bank facing an energy shock, French fiscal stress and a market that still expects further tightening.
The official language calls this a “meeting-by-meeting” approach. In practice, it means the ECB is buying time while households and governments absorb the cost.
Holding rates avoids an immediate blow. It does not resolve the underlying crisis. Europe remains dependent on volatile energy routes, divided by unequal debt burdens and committed to a monetary framework that transfers the price of war downward. The next decision will come with the same question in sharper form: how much economic damage will the ECB accept to defend its inflation target?
Sources: European Central Bank · Reuters · The Wall Street Journal · Associated Press · Photo licenses: ECB headquarters photograph · French Finance Ministry photograph


Comments